Category: Bookkeeping

  • What is Form W-7: Application for IRS Individual Taxpayer Identification Number

    apply for itin in person

    ITIN Expiration Frequently Asked Questions and Understanding Your IRS Individual Taxpayer Identification Number ITIN PDF have additional information. Taxpayers and their representatives can read ITIN Reminders for Tax Professionals for the latest information on filing tax returns using ITINs. Employees at IRS Taxpayer Assistance Centers (TACs) can review your original documents and certified copies from the issuing agencies required to apply and renew for Individual Taxpayer Identification Numbers (ITINs).

    1. An ITIN may be assigned to an alien dependent from Canada or Mexico if that dependent qualifies a taxpayer for a child or dependent care credit (claimed on Form 2441).
    2. LITCs represent individuals whose income is below a certain level and who need to resolve tax problems with the IRS.
    3. ITINs that have not been used on a tax return for Tax Year 2020, Tax Year 2021 or Tax Year 2022 will expire December 31, 2023.
    4. For more information or to find an LITC near you, see the LITC page on the TAS website or Publication 4134, Low Income Taxpayer Clinic List.

    Can I get Social Security benefits with an ITIN?

    This can include both U.S. citizens and non-citizens such as U.S. nationals and permanent residents. These people use their Social Security written down value method wdv of depreciation numbers to identify themselves when filing their taxes. Low Income Taxpayer Clinics (LITCs) are independent from the IRS and TAS.

    Conclusions are based on information provided by you in response to the questions you answered. Answers do not constitute written advice in response to a specific written request of the taxpayer within the meaning of section 6404(f) of the Internal Revenue Code. As long as you qualify for a refund, and you have filed your taxes correctly, then yes.

    You can file Form W-7, Application for IRS Individual Taxpayer Identification Number (ITIN), with your federal income tax return. You must also include original documentation or certified copies from the issuing agency to prove identity and foreign status. You will usually file an ITIN application, Form W-7, Application for IRS Individual Taxpayer Identification Number, with your first tax return, which you must file as a paper return, not electronically. All the exceptions are listed in the ITIN application instructions. Those affected by Hurricane Beryl in Texas and Hurricane Debby in some states in the Southeastern United States have more time to file federal tax returns and make certain tax payments. The additional time allowed by the IRS includes tax returns that were extended by the original April 15, 2024, deadline as well as certain payments that are normally due after the storms impacted these people.
    apply for itin in person

    ITIN holders can access their online account

    And if you want to file your own taxes, you can still feel confident you’ll do them right with TurboTax as we guide you step by step. No matter which way you file, we guarantee 100% accuracy and your maximum refund. An Individual Taxpayer Identification Number (ITIN) is a tax processing number issued by the Internal Revenue Service. You will only file a tax return to the address above once, when you file Form W-7 to get an ITIN. In subsequent years, when you have an ITIN, you will file your tax return as directed in the form instructions. In general, only people who are authorized to work in the United States are eligible to have a Social Security number.

    Am I eligible to apply for an individual taxpayer identification number?

    A tax return accompanied by one or more W-7 forms cannot be submitted electronically. You can submit it in person at any IRS Taxpayer Assistance Center that performs in-person document reviews; most major cities have such assistance centers, and there is at least one center in every state. Many applicants have reported the IRS lost their passports or other valuable and hard-to-replace identification documents. Consider getting certified copies or using one of the application methods listed below, rather than mailing original identification documents to the IRS.

    The Individual Tax Identification Number, or ITIN, allows taxpayers who don’t have qualitative characteristics of financial statements a Social Security Number (SSN) to file income tax returns. Unlike other forms of ID, ITINs only have one purpose—tax filing and reporting. Having an ITIN number won’t make you eligible for benefits, such as Social Security or earned income credits that provide refunds to some low-income filers. IRS issues ITINs to help individuals comply with the U.S. tax laws, and to provide a means to efficiently process and account for tax returns and payments for those not eligible for Social Security numbers. They are issued regardless of immigration status, because both resident and nonresident aliens may have a U.S. filing or reporting requirement under the Internal Revenue Code. ITINs do not serve any purpose other than federal tax reporting.

    Who Needs an ITIN or Individual Tax Identification Number?

    Instead, they can apply for an Individual Taxpayer Identification Number, or ITIN, by submitting Form W-7 to the IRS. If none of the in-person options work for you, you can still submit your application by mail. We where current property are situated on the steadiness sheet — accountingtools strongly suggest that you get certified copies of all your documents instead of sending originals.

    If you’re unsure whether you need an ITIN, check with your employer.
  • The 10 Best Online Bookkeeping Services of 2022

    booking keeping services

    You’ll also get burn rate calculations, which is helpful for startups that need to closely track their spending. You don’t have to hire someone to come into your office to have an in-house bookkeeper — many are virtual. Using virtual bookkeeping allows you to outsource the day-to-day tasks that are a challenge to keep up with while also having a direct contact to ask questions of. Virtual bookkeepers will manage your business’s financial details and make sure your tax information is accurate, which makes the financial side of business a lot easier. Bench’s Essential plan is $249 a month and includes monthly bookkeeping and a dedicated bookkeeping team.

    Best Online Bookkeeping Services of 2024

    Join over 25,000 US-based business owners who have streamlined their finances and have grown their businesses with Bench. A downside of Pilot is that the main way to communicate with finance experts is via email, which can make it harder to get quick replies. You also guide to financial statement services – gra cpa can’t pay on a month-to-month basis, unlike a few others on our list. But if you have the time to dedicate to updating your books regularly, doing your own bookkeeping may be feasible.

    FreshBooks’ online bookkeeping services help you protect your profits, save you time, and grow your business. In collaboration with Bench (more on them later), we offer expert virtual bookkeeping systems and tax services support. The two platforms work together seamlessly, allowing you to effortlessly bill and invoice with FreshBooks, and automatically see that income reflected in your bookkeeping.

    1. Your bookkeeper will assist you with setting up your chart of accounts, connecting your banks, and creating a plan to clean up any existing data.
    2. If you are behind on your bookkeeping, you can use Bench’s Catch Up and Retro bookkeeping services to bring your books up to date.
    3. However, credit score alone does not guarantee or imply approval for any credit card, financing, or service offer.
    4. Otherwise, monthly pricing starts at $399 and weekly pricing starts at $549 per month.
    5. This enables you and your Bench team to work together seamlessly from the start.

    Online Bookkeeping by Bench

    booking keeping services

    While it doesn’t offer many of the advanced tools that other online bookkeeping services provide, it is easy to use and has a quick setup process. At the very least, you can expect most bookkeeping services to input transactions, reconcile accounts and send you financial statements regularly. Most services touch base monthly, but in some cases, you can pay extra to receive weekly reports. Depending on the company, you can speak with your bookkeeper (or team of bookkeepers) as often as you’d like or at least a few times per month.

    With an accurate record of all transactions, you can easily discover any discrepancies between financial statements and what’s been recorded. This will allow you to quickly catch any errors that could become an issue down the road. By logging and keeping track of all financial transactions, you will have easy access to any financial information you might need. To make it even easier, bookkeepers often group transactions into categories. When you think of bookkeeping, you may think it’s all just numbers and spreadsheets.

    Do you need add-on services outside of basic bookkeeping tasks?

    This service may be helpful in aiding you in considering your startup’s financial options. Every report accessible in the Bench platform can be exported to an Excel file for easy sharing with anyone from business partners to accountants. The most common mistakes are mixing personal and business finances, leaving taxes to the last minute, missing out on deductions, and not retaining records for long enough. You may be hoping for the best and have a few college courses in your back pocket. Even with these tools, you may not have the expertise you need to handle the responsibilities of a bookkeeper.

    If you only need periodic help, pay as you go for $49 per month plus $125 per hour for support. Otherwise, monthly pricing starts at $399 and weekly pricing starts at $549 per month. Many small businesses enjoy having a dedicated team to handle all of their monthly bookkeeping, and cashier’s check vs money order using accounting software is a smart addition. Don’t miss the accounting software resources put together by Nav experts. IgniteSpot Accounting boasts a more personalized approach to outsourced accounting services. Its bookkeeping packages include certified virtual bookkeepers and a dedicated accountant for your business.

    How to Choose a Virtual Bookkeeper for Your Business

    Our expert CPAs and QuickBooks ProAdvisors average 15 years of experience working with small businesses across various industries. The double-entry system of bookkeeping is common in accounting software programs like QuickBooks. With this method, bookkeepers record transactions under expense or income. Then they create a second entry to classify the transaction on the appropriate account. Accounting is the umbrella term for all processes related to recording a business’s financial transactions, whereas bookkeeping is an integral part of the accounting process.

    She has owned Check Yourself, a bookkeeping and payroll service that specializes in small business, for over twenty years. She holds a Bachelor’s degree from UCLA and has served on the Board of the National Association of Women Business Owners. She also regularly writes about business for various consumer publications. In addition, you’ll need a subscription to Wave Accounting, which is free which financial statement is the most important for one user and $16 a month for unlimited users. To learn more, read our review of Wave Accounting, which is linked above. A free live bookkeeping consultation is required before signing up, and services are billed annually.

  • Pay or adjust payroll liabilities in QuickBooks Desktop

    payroll liabilities quickbooks

    Automate the payroll process so you can save time and focus on growing your business. Payroll software like QuickBooks Payroll can help streamline your process and seamlessly track liabilities and expenses. Use payroll software to generate a payroll-liability balance report each time you process payroll. For instance, if an employee’s vacation pay is adjusted retroactively, it would prompt a change in the accrued vacation liability. Similarly, if a new tax law is enacted, it may lead to adjustments in tax calculations and withholdings.

    1. A very important part of managing payroll is tracking and paying payroll liabilities.
    2. When your payroll liabilities are incorrect, you can do a liability adjustment to fix them.
    3. Configuring payroll liabilities in QuickBooks Online entails the setup of tax forms, ensuring accurate financial reporting, and adherence to compliance requirements.
    4. When comparing paying payroll liabilities in QuickBooks Online and QuickBooks Desktop, distinct differences emerge in the user interface, available payment options, and management of tax deadlines.
    5. Payroll liabilities occur throughout the payroll process, even before you pay employees.

    Payroll processing is complex, meaning you’re likely to struggle to stay on top of the process. A very important part of managing payroll is tracking and paying payroll liabilities. Managing payroll is one of the top challenges for small business owners, according to a Justworks and The Harris Poll survey. QuickBooks Desktop offers robust financial reporting tools, allowing users to generate diverse and customized reports to analyze payroll liabilities. In contrast, QuickBooks Online provides a more streamlined approach, with access to standard financial reports.

    From setting up payroll items to creating scheduled liabilities payments, we will cover every step in detail, ensuring that you have a thorough understanding of the processes involved. We will highlight the key differences between paying payroll liabilities in QuickBooks Online and QuickBooks Desktop, shedding light on aspects such as user interface, payment options, and reporting capabilities. Implementing scheduled liabilities payments in QuickBooks Online streamlines tax reporting and compliance adherence by automating the timely allocation of funds towards payroll liabilities. This feature minimizes the risk of missed contribution margin payments and facilitates accurate tax filings.

    How to Set Up Payroll Liabilities in QuickBooks Desktop?

    Once this is completed, the adjusted figures need to be accurately entered into the payroll system to ensure that all liabilities are properly accounted for and reflect the changes that have been made. Compliance adherence ensures that businesses meet legal requirements and avoid potential penalties and fines, promoting financial stability and seamless operations. When your payroll liabilities are incorrect, you can do a liability adjustment to fix them. Now you’ll need to enter the rest of your employees’ personal data and answer some other questions about how you want to run payroll going forward. You’ll only need global consumer banking to worry about this the first time you run payroll for a particular employee.

    Step 3: Remit the payroll liabilities for the period

    By accurately inputting employee information, wage rates, deductions, and taxes, QuickBooks Desktop facilitates precise calculation and recording of payroll liabilities. The software allows for customization of payroll items to suit specific business needs, contributing to meticulous financial record-keeping. The reporting capabilities of QuickBooks Online and QuickBooks Desktop for payroll liabilities management differ in terms of financial reporting and tax-related functionalities. Understanding these disparities is essential for optimizing financial and tax reporting accuracy.

    First, the software will ask you for a date to run payroll and if it’s scheduled or unscheduled. If you’re setting up a new payroll schedule for an employee, you’ll be taken to an additional screen so that you enter in the information to allow for future automation. If you’re not sure where to find it, check out the setup guide from QuickBooks for a guide to the dashboard.

    If you’re looking for automated payroll and tax filing, plus next-day direct deposit, QuickBooks remains an industry-leading choice. The IRS and state agencies have specific deposit schedules for payroll taxes—adhere to these schedules to avoid penalties and interest. QuickBooks Online offers a cloud-based interface that allows users to access payroll features from any location with internet connectivity. By utilizing scheduled payments, businesses can enhance their cash flow management and avoid penalties for late payments, ultimately contributing to improved financial stability and regulatory compliance.

    Step 2: Enter Year-to-Date Information

    payroll liabilities quickbooks

    This process necessitates a thorough review of the current payroll settings to identify areas that require modification. For example, if there are changes in tax laws, the tax categories must be adjusted accordingly to ensure compliance. QuickBooks offers options to customize withholding rates based on the latest regulations, and it also allows flexibility in adjusting employer contributions. It is crucial to consider the implications of operating income these changes, as they may affect employee pay, tax reporting, and overall financial management. Recording manual payments for payroll liabilities in QuickBooks Desktop enables accurate tracking of tax deposits and ensures meticulous management of financial records.

    The electronic payment processing feature enables you to conveniently pay employees and taxes online, saving time and reducing manual errors. QuickBooks Online’s tax deduction capabilities automatically calculate and withhold the required taxes, simplifying the complex task of payroll taxation. Establishing payroll items within QuickBooks Online involves configuring essential components such as employee records, automation of transactions, and categorization of payroll expenses.

  • What is Outsourced Accounting? & How Does It Work?

    outsource accounts

    As your company grows, you may find it harder to keep up with all your accounting responsibilities, such as payroll, tax filing, and reconciling your accounts. As the owner, you want to grow your business and focus on the vision of the company itself. This can be done for quite a low hourly rate depending on where you’re comfortable outsourcing to.

    By leveraging accounting firms’ specialized knowledge and resources, businesses can optimize their financial management and achieve long-term success. By outsourcing accounting functions, organizations can leverage the expertise of accounting professionals who stay up to date with changing regulations. To learn more about LBMC’s outsourced accounting services, contact an advisor today. That means you won’t get to spend as much face-to-face time with your accountant as you would if they were your employee. If you’re bringing in an outsourced controller to help manage your existing team, it’s necessary to carefully consider what this relationship will look like.

    1. These resources may be particularly beneficial for small and mid-sized businesses that may not have robust IT departments or stringent confidentiality measures.
    2. When working with any service provider, it’s important to establish service-level agreements (SLAs).
    3. Your company can gain game-changing financial insights and unlock benefits including increased cash flow and higher profit margins.
    4. Let’s dive into the transformative benefits and the essential steps for fully leveraging outsourcing for your business.
    5. As businesses grow or experience fluctuations in accounting requirements, the outsourcing arrangement can be easily adjusted.

    You should also specify what happens if the provider fails to meet any of these expectations. This could be anything from a partial refund for a departments to manage the purchasing late delivery, to termination of the contract in more extreme cases. That’s why many businesses — from fledgeling startups to multinational enterprises — opt to outsource instead. Expanded Employee Retention Credit (ERC) & how our professionals can assist you. Leave the administrative load with us and get more time to focus on revenue-generating activities. So you shouldn’t feel like you have to handle all the finances in your small business.

    Functions That Could be Outsource to Accounting Firms

    Even if some employees are absent, the stress of covering up does not land on a sole supervisor. Most in-house teams have a financial supervisor, such as the CFO, to manage issues when employees aren’t present. Additionally, since the outsourcing team only works on your accounts payable, they can deliver results much faster. This way, companies gain huge cost reductions from saved time and improved productivity. To learn more about how we can help, speak to one of our friendly experts today — or check out our in-depth payroll processing guide. We do all the heavy lifting for you, giving you peace of mind and allowing you to focus your time, money, and resources on running and growing your business.

    To make the best possible financial decisions, it’s important to fully understand your company’s financial position and analyze potential outcomes. Almost all companies must pay taxes on their income, regardless of where they are headquartered. But preparing taxes and complying with regulations can be tricky, especially if your business has a complex corporate structure. If you’re hiring across borders, you’ll have to recruit in-house accountants in all the countries you’re onboarding in.

    Accounts receivable and accounts payable management

    outsource accounts

    Depending on what is futa definition and how to calculate futa liability the industry standards and your outsourcing provider, the data may be stored on internal servers or even on the cloud. This could increase your data’s accessibility — making it prone to unauthorized access. Data security is a serious concern for any business, as breaches can lead to financial losses, legal issues, and reputational damage.

    Common Outsourced Accounting Myths

    Apart from enhanced security and access to experts, businesses have significantly benefited from outsourced accounting. To elaborate on how it helps organizations, this guide takes a look at what outsourced accounting is and its top benefits. In today’s uncertain market, your organization might be drowning in a mess of financial transactions, overworked team members and a lack of time management driven by inefficient processes.

    It enhances data security, ensures compliance, and enables organizations to adapt to changing accounting needs. Outsourced accounting is when an organization delegates its accounting and financial functions to an external third-party service provider. Firstly, establish whether the outsourced CFO you’re interested in working with has a proven track record in your industry.

    Recruiting, onboarding, and managing an internal finance and accounting team takes up a significant amount of time. By partnering with an outsourced accounting services firm, business owners can free up the time they would have spent managing their accounting department to focus on running their business. There are a number of benefits that businesses can unearned revenue realize from partnering with an outsourced accounting services firm. In-house accounting employees typically require a full-time salary and employee benefits, while outsourced accounting services can be tailored to the specific needs of a company. Outsourcing accounting services is a powerful strategy for businesses aiming to streamline operations and boost financial management. If you need a bit more support, Bench also offers outsourced accounting services, including tax prep and tax filing.

    When working with any service provider, it’s important to establish service-level agreements (SLAs). These lay out the specifics of the services provided and keep both parties on the same page. Many companies outsource this task to experienced auditors, who can independently assess your company’s financial processes and even advise on ways to improve. The amount of work you have available may not justify hiring one in-house, even on a part-time basis. Outsourced accounting service costs vary based on the scope of the services needed and the size of the business. Costs may be charged on a flexible, hourly basis or structured within a fixed monthly package.

  • 6 Best Online Accounting Firms for Small Business of 2023

    best outsource cpa for startup

    And when you use us as your bookkeeper, we set up and keep up-to-date a due diligence folder so you can get that next round of fundraising. When early-stage companies get acquired by massive public companies or sophisticated venture capitalists, they need specialized accounting consulting and finance help. I have to say, when I get on a diligence call with a big company that is acquiring one of our clients, and me and my team make it clear that we are CPAs, it really helps change the tone of the conversation. The acquiring company realizes that they are dealing with a professional team of world-class accountants focused on serving startup clients.

    AI’s Impact on the Future of Finance and Accounting

    In order to provide useful guidance, an outsourced CFO service will need extensive knowledge of your business model, capacity, and how your team operates. Your team will need to fully understand your startup, so set reasonable expectations. However, if you choose an outsourced CFO without the relevant experience, the support they can offer will be limited. For instance, if your business is a SaaS startup and you work with a CFO specializing in direct-to-consumer businesses, chances are they’ll only be able to act as an adviser rather than being a hands-on partner. The budget sets targets for how the startup should perform each month in order to achieve the results in your projections.

    Case Studies With Hundreds of Startups

    Whether you’re a small business or a large international firm, they’ve got you covered with their dedicated team of skilled accountants, bookkeepers, finance and administration professionals. Ultimately, the best online accounting service for a startup depends on factors such as budget, ease of use, required features, and scalability. It’s essential to evaluate each option based on the startup’s specific needs and objectives before deciding. Additionally, many of these services offer free trials or demos, allowing startups to test the platform before committing to a subscription.

    Bookkeeper360: Best for hourly bookkeeping

    best outsource cpa for startup

    We are currently ranked as the 13th best startup website in the world and are paving our way to the top. What’s even better is that TOA Global’s team is well-versed in popular accounting software like FreshBooks, QuickBooks, Xero, and MYOB. So, if you want to hire accounting and finance teams who speak in language, work in your time zone, and are rigorously vetted, then 1840 & Company can be worth your time. First, you’ll connect with a Solutions Consultant to discuss your specific needs to determine if Belay is the right fit for you. And if you indeed are, then as part of the next step, you’ll be assigned a Client Success Consultant. You’ll then dive deep into your tasks, tools, culture, and requirements with the Client Success Consultant to ensure they find the right talent for you.

    • Yes, venture-backed high-growth businesses should have as close to GAAP financials as possible.
    • Imagine being able to work with the top 3% accounting experts from around the world.
    • With accrual accounting, you would recognize $10,000 of that revenue each month.
    • Scenario modeling involves creating alternative projections that show how your company is likely to perform under various conditions.
    • Because we are more of a long-term finance partner (which is what you want) compared to a short term “outsourced” bookkeeping firm, all of our engagements are custom.

    If You Need Location-Specific Accounting Services

    Technical debt is incurred when you’re working very fast to develop a prototype or working model, and you’re not building everything perfectly. Accounting debt is a similar concept – startups can often ignore creating their accounting infrastructure to focus on their technology or customers. But eventually you’ll need to set up your accounting systems, and the longer you wait, the more you’ll have to go back and fix, just http://hilaryclub.ru/page,1,2,2118-o-sayte.html like technical debt. The good news is that by taking some simple steps early, founders can avoid accumulating a lot of accounting debt. Startups need more than a robot to reconcile the accounts, they need a trusted advisor who is in tune with their unique growth path. Available to answer questions, available to update numbers as new data is produced, available to set up the right systems for a high growth company.

    best outsource cpa for startup

    Shopify Capital: Best Funding for Your E-commerce Business

    As a startup, you have to focus on your product and customers, and Kruze takes care of everything else (which is a massive sigh of relief). This tool can help founders estimate reasonable pay based on the amount of capital that they’ve raised, the stage of their business and their company’s industry. Unprofitable startups can seriously reduce their burn rate – up to $500,000 per year. Our entry-level package gives early-stage founders the accounting expertise they need. Startups are more successful when they can accurately budget and plan for growth. Our philosophy is to research, curate, and provide the best startup feeds and resources to help you succeed in your venture.

    What should I expect in terms of cost when hiring an outsourced CPA service?

    best outsource cpa for startup

    Outsourcing CPA services can be more cost-effective than hiring full-time in-house accountants or establishing an internal outsourced accounting for small business  department. Startups can access top-tier expertise on a flexible basis, paying only for the services they need when they need them. CPAs specialize in ensuring compliance with tax laws, regulations, and financial reporting standards.

    best outsource cpa for startup

    Additionally, outsourcing can help small businesses stay compliant with regulations and avoid costly mistakes. By outsourcing accounting services, small businesses can focus on their core competencies while leaving the accounting to the experts. It is important to take the time to compare different http://www.nneformat.ru/gbook/?p=9 CPA service providers to find the one that is the best fit for your startup. Kruze Consulting is one such provider that offers outsourced CFO, tax, and bookkeeping services to startups. They have a team of experts who are committed to providing high-quality services to their clients.

    Business Systems and Process Improvements

    Ignite Spot Accounting delivers heftier reports than many other cloud accounting providers we checked out for this piece. Along with typical financial reporting (like profit and loss reports and balance sheets), you’ll get a KPI (key performance indicator) http://swlesson-mpl.ru/indexphp/2009-04-05-08-21-44/35-2009-04-05-10-50-51/287-solidworks-certification.html report and profitability analysis, among others. You have to enter more information about your needs to get a quote—which is useful if you want truly customized services but unhelpful if you’d rather choose a basic plan out of a lineup.

  • 4 Accounting & Compliance Considerations for Oil & Gas Companies

    accounting in oil and gas industry

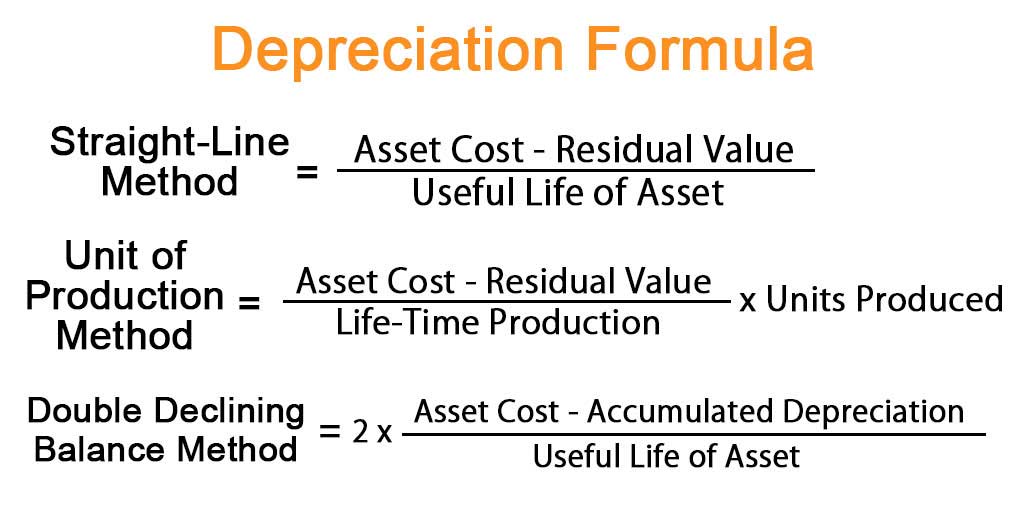
    Depreciation and amortization, on the other hand, apply to tangible and intangible assets, respectively. Depreciation involves the systematic allocation of the cost of physical assets, such as drilling rigs and production facilities, over their useful lives. Both processes ensure that https://www.bookstime.com/ the costs of these assets are matched with the revenues they generate, providing a more accurate picture of a company’s financial performance. The choice of depreciation and amortization methods, such as straight-line or declining balance, can significantly influence financial statements and tax liabilities.

    Cost Management and Analysis

    Instead, you assume that the company adds nothing to its reserves and that https://x.com/BooksTimeInc it produces 100% of its reserves until it runs out of natural resources completely. For E&P companies, there’s an alternate intrinsic valuation methodology called the Net Asset Value (NAV) model that often gives more accurate results. You always capitalize acquisitions and development (actually constructing the field or well), and you always expense production. So you might create a “low” scenario where oil prices are, say, $40 per barrel, a “middle” scenario where oil prices are $70 per barrel, and a “high” scenario where oil prices are $100 per barrel.

    How will you record embedded leases under an operating agreement?

    accounting in oil and gas industry

    Fortunately, we know a thing or two about production of accounting software for oil and gas and want to share some of our insights and best practices so that you can make an informed decision. Oil and gas accountants play a pivotal role in the energy industry by ensuring financial stability, compliance, and efficiency within oil and gas companies. By adhering to best practices and leveraging industry-specific knowledge, accountants contribute to the long-term success and sustainability of oil and gas operations.

    Specialized Training and Education

    Any actual difference comes down to an individual company’s overall business processes and how they meet their customers’ needs. In May 2020, the SEC adopted amendments to the required financial disclosures about acquired and disposed businesses. The amendments will be effective on Jan. 1, 2021, but early voluntary compliance is permitted.

    accounting in oil and gas industry

    Impairment of Oil and Gas Assets

    It ensures transparent financial reporting, compliance with regulations, and strategic decision-making. As an intricate discipline, oil and gas accounting plays a pivotal role in valuing assets, managing risks, and supporting sustainable practices in the exploration, extraction, and production of oil and gas resources. The financial results of a manufacturing company are impacted by depreciation expense for plant, property, and equipment. In addition to cost allocation, joint venture accounting must address the treatment of joint venture assets and liabilities.

    • Companies often employ specialized software like Quorum Joint Venture Accounting or P2 BOLO to manage these complex transactions, ensuring that all parties receive timely and accurate financial information.
    • But then if prices go up, it becomes cost-effective to use more expensive techniques, like injecting steam into the ground.
    • Regular audits help identify areas for improvement and ensure adherence to industry standards.
    • For example, what if a well site extracts oil or gas and then turns around and uses some of it to power the machinery at the well site?
    • The oil and gas industry encompasses exploration, extraction, refining, and distribution of oil and gas resources.

    Explore essential oil and gas accounting practices, from cost types to revenue recognition and financial reporting standards. Stakeholders rely on financial statements to assess the financial health of oil and gas companies. Proper accounting practices build trust among investors, regulators, and the public, fostering confidence in the industry. Oil and gas companies employ the use of strategic service contracts as part of their operations. The new IFRS 16 and ASC 842 standards require companies to record leases as right-of-use assets based on economic benefit. This means oil and gas companies need to look at their service agreements and determine whether they contain embedded leases that must be placed on balance sheets.

    accounting in oil and gas industry

    In the oil and gas industry, it is common for multiple entities to collaborate on exploration, development, and production projects. Each partner’s share of revenue must be accurately calculated and reported, taking into account the specific terms of the joint venture agreement. This often involves detailed tracking of costs, production volumes, and sales proceeds, ensuring that each party receives its fair share of the revenue. Depletion, depreciation, and amortization (DD&A) are critical components of financial accounting in the oil and gas industry, reflecting the gradual consumption of capital assets over time. Depletion pertains specifically to the reduction in the value of natural resources as they are extracted, while depreciation and amortization apply to tangible and intangible assets, respectively. Accurate accounting in oil and gas industry DD&A calculations are essential for providing a realistic view of a company’s financial health and asset value.

    We also offer business advisory support to companies in the oil and gas sector, including those in trucking services for gas transportation. Let’s have a more detailed look at what benefits oil and gas accounting software provides to businesses and business owners, and how to use it properly. What if you then shift that oil or gas to a nearby property and use it to power the equipment over there? That other property may have different ownership percentages, and perhaps some of the interest owners over there aren’t even the same folks as the ones involved with the first property. So now, you have to record the oil and gas coming out of the source well as revenue, and pay royalties and taxes on it, and then charge it to expense at the receiving site. When a reservoir is first discovered, there’s a certain amount of oil and gas in there, but not all of it is recoverable.

    accounting in oil and gas industry

    HAVE TAX QUESTIONS? WE HAVE ANSWERS!

    These assets and liabilities are typically recorded on the balance sheet of the operator, who manages the day-to-day operations of the joint venture. The operator is responsible for maintaining detailed records of all transactions and providing regular financial reports to the non-operating partners. These reports enable the non-operating partners to account for their share of the joint venture’s activities in their financial statements.